

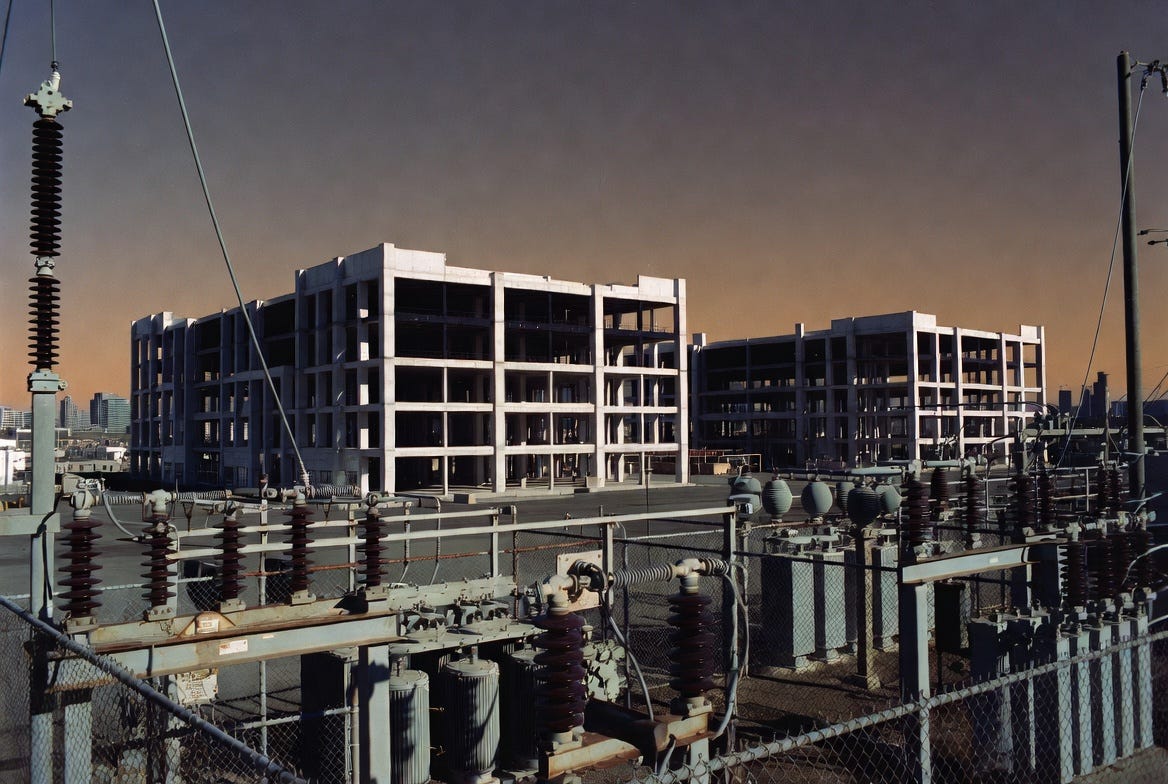
Two fully built-out data centers are sitting offline in Santa Clara, within walking distance of Nvidia’s headquarters. They have the chips. They have the buildings. They have the money. What they don’t have is a power connection.
A YouTube channel called “How Money Works” recently built a sixteen-minute argument around that single fact. The video is well-produced, correctly cites Sightline Climate’s data that roughly half of the 2026 US data-center pipeline has slipped, and calls the situation a “logical paradox.” Nvidia is shipping GPUs faster than sites can be brought online. Inventory has doubled. Customers are slow to pay. Jensen Huang’s claim that Nvidia shipped 10 gigawatts of GPUs in 2025 exceeds Goldman Sachs’ estimate that only 7.7 gigawatts of AI data centers are operational worldwide. The narrator invokes Michael Burry, the dot-com bubble, and the inevitable correction.
Half of the video is right. The delivery layer is a real bottleneck. Transformer lead times went from four-to-six weeks in 2020 to three-to-four years in 2026. Costs are up 80%. Seventy percent of US transmission lines and large transformers are over twenty-five years old. Oracle and OpenAI just shelved the Stargate expansion in Abilene. These are not minor frictions.
The other half is wrong in the specific way that drives bad policy. The video frames the tension as AI ambition versus economic reality — and that framing produces a bubble narrative with a predictable prescription: moratoriums, restrictions, slow the build-out, wait for the correction. But the data it cites point to a completely different diagnosis. The correct tension is exponential generation abundance versus linear delivery infrastructure. Same facts. Entirely different prescription.
The discipline that separates the two is the “compared to what?” test. Every claim in the skeptic narrative fails at least one version of it. Here are three.
Question One: Compared to What? (Electricity Prices)
In 2025, Rhode Island residents saw their household electricity bills rise 8.4%. Take a guess how many AI data centers are in Rhode Island. The answer is approximately zero. Maine, up 8.1% — also effectively no data centers. Massachusetts, up 7.7% — the same. Eversource Massachusetts supply rates alone rose 12.3% on a single day in August 2025. None of it is caused by AI load.
Now look at the states with the heaviest data-center concentration. Texas: 16.18¢ per kilowatt-hour in 2026. Georgia: 15.5¢. Arizona: 15.2¢. The US national average is 17.45¢. The states with the most AI data centers are paying less than the national average. The states with no data centers are paying the highest rates in the country.
The Institute for Energy Research ran the full fifty-state test in 2025: the top-ten data-center states averaged 14.46¢/kWh; all other states averaged 14.39¢/kWh. The difference is statistically indistinguishable. Lawrence Berkeley National Laboratory’s 2024 report puts total US data-center electricity consumption at 4.4% of the national total in 2023, projected to reach 6.7–12% by 2028. Carnegie Mellon’s analysis via Brookings finds that data centers and crypto combined could add approximately 8% to average US bills by 2030, but 25%+ only in the highest-concentration markets like Northern Virginia. The effect is localized, not national.
The most striking data point comes from December 2025, when Reason magazine reported that Pacific Gas and Electric’s own projections show incremental data-center load could reduce average California household bills by up to 2%. Steady baseload demand spreads fixed infrastructure costs over more throughput. That is the opposite of the prevailing narrative.
So what is actually driving household rate increases? Everything except AI. FERC data show US electric demand grew at a 0.5% compound annual rate from 2014 to 2024, while transmission and distribution capital spending grew at 8.9% — seventeen times faster. New England transmission costs rose 800% between 2004 and 2023. California has authorized $27 billion in wildfire-hardening capex from 2019 through 2023, with PG&E alone exceeding $3 billion in 2023. ISO-NE’s winter gas supply constraints drive independent New England power spikes. And PJM’s capacity market design produced the single largest factor in the recent surge: the 2025/26 Base Residual Auction cleared at $269.92 per megawatt-day, up from $28.92 — a 9.3-fold jump driven by the auction’s administrative simulation, not by realized data-center load. The SemiAnalysis research team documented this in detail. The PJM Market Monitor itself attributes only about 40% of the 2025/26 capacity-cost increase to data centers, meaning 60% comes from supply retirements, reliability-requirement resets, and auction design.
The narrative that AI is raising household bills is doing the exact job a misdiagnosis always does in policy: it directs political energy toward a misidentified cause and produces responses that make the actual problem worse. Moratoriums against data centers do not replace a transformer whose lead time has quadrupled. They just move the investment to the next state.
Question Two: Compared to What? (Gas Prices)
On April 20, 2026 — the day before this article was drafted — the Henry Hub natural gas spot price closed at $2.71 per million British thermal units. That is slightly above the 2024 annual average of $2.21 — which the EIA called "the lowest average annual price in inflation-adjusted dollars ever reported" — and still below the 2015–2019 average of $2.77. It is roughly one-quarter of the 2008 peak near $12 and less than a third of the 2022 Ukraine-war peak of $9. The April 2026 EIA Short-Term Energy Outlook forecasts Henry Hub averaging $3.67 in 2026 and $3.59 in 2027 — both revised downward from earlier projections.
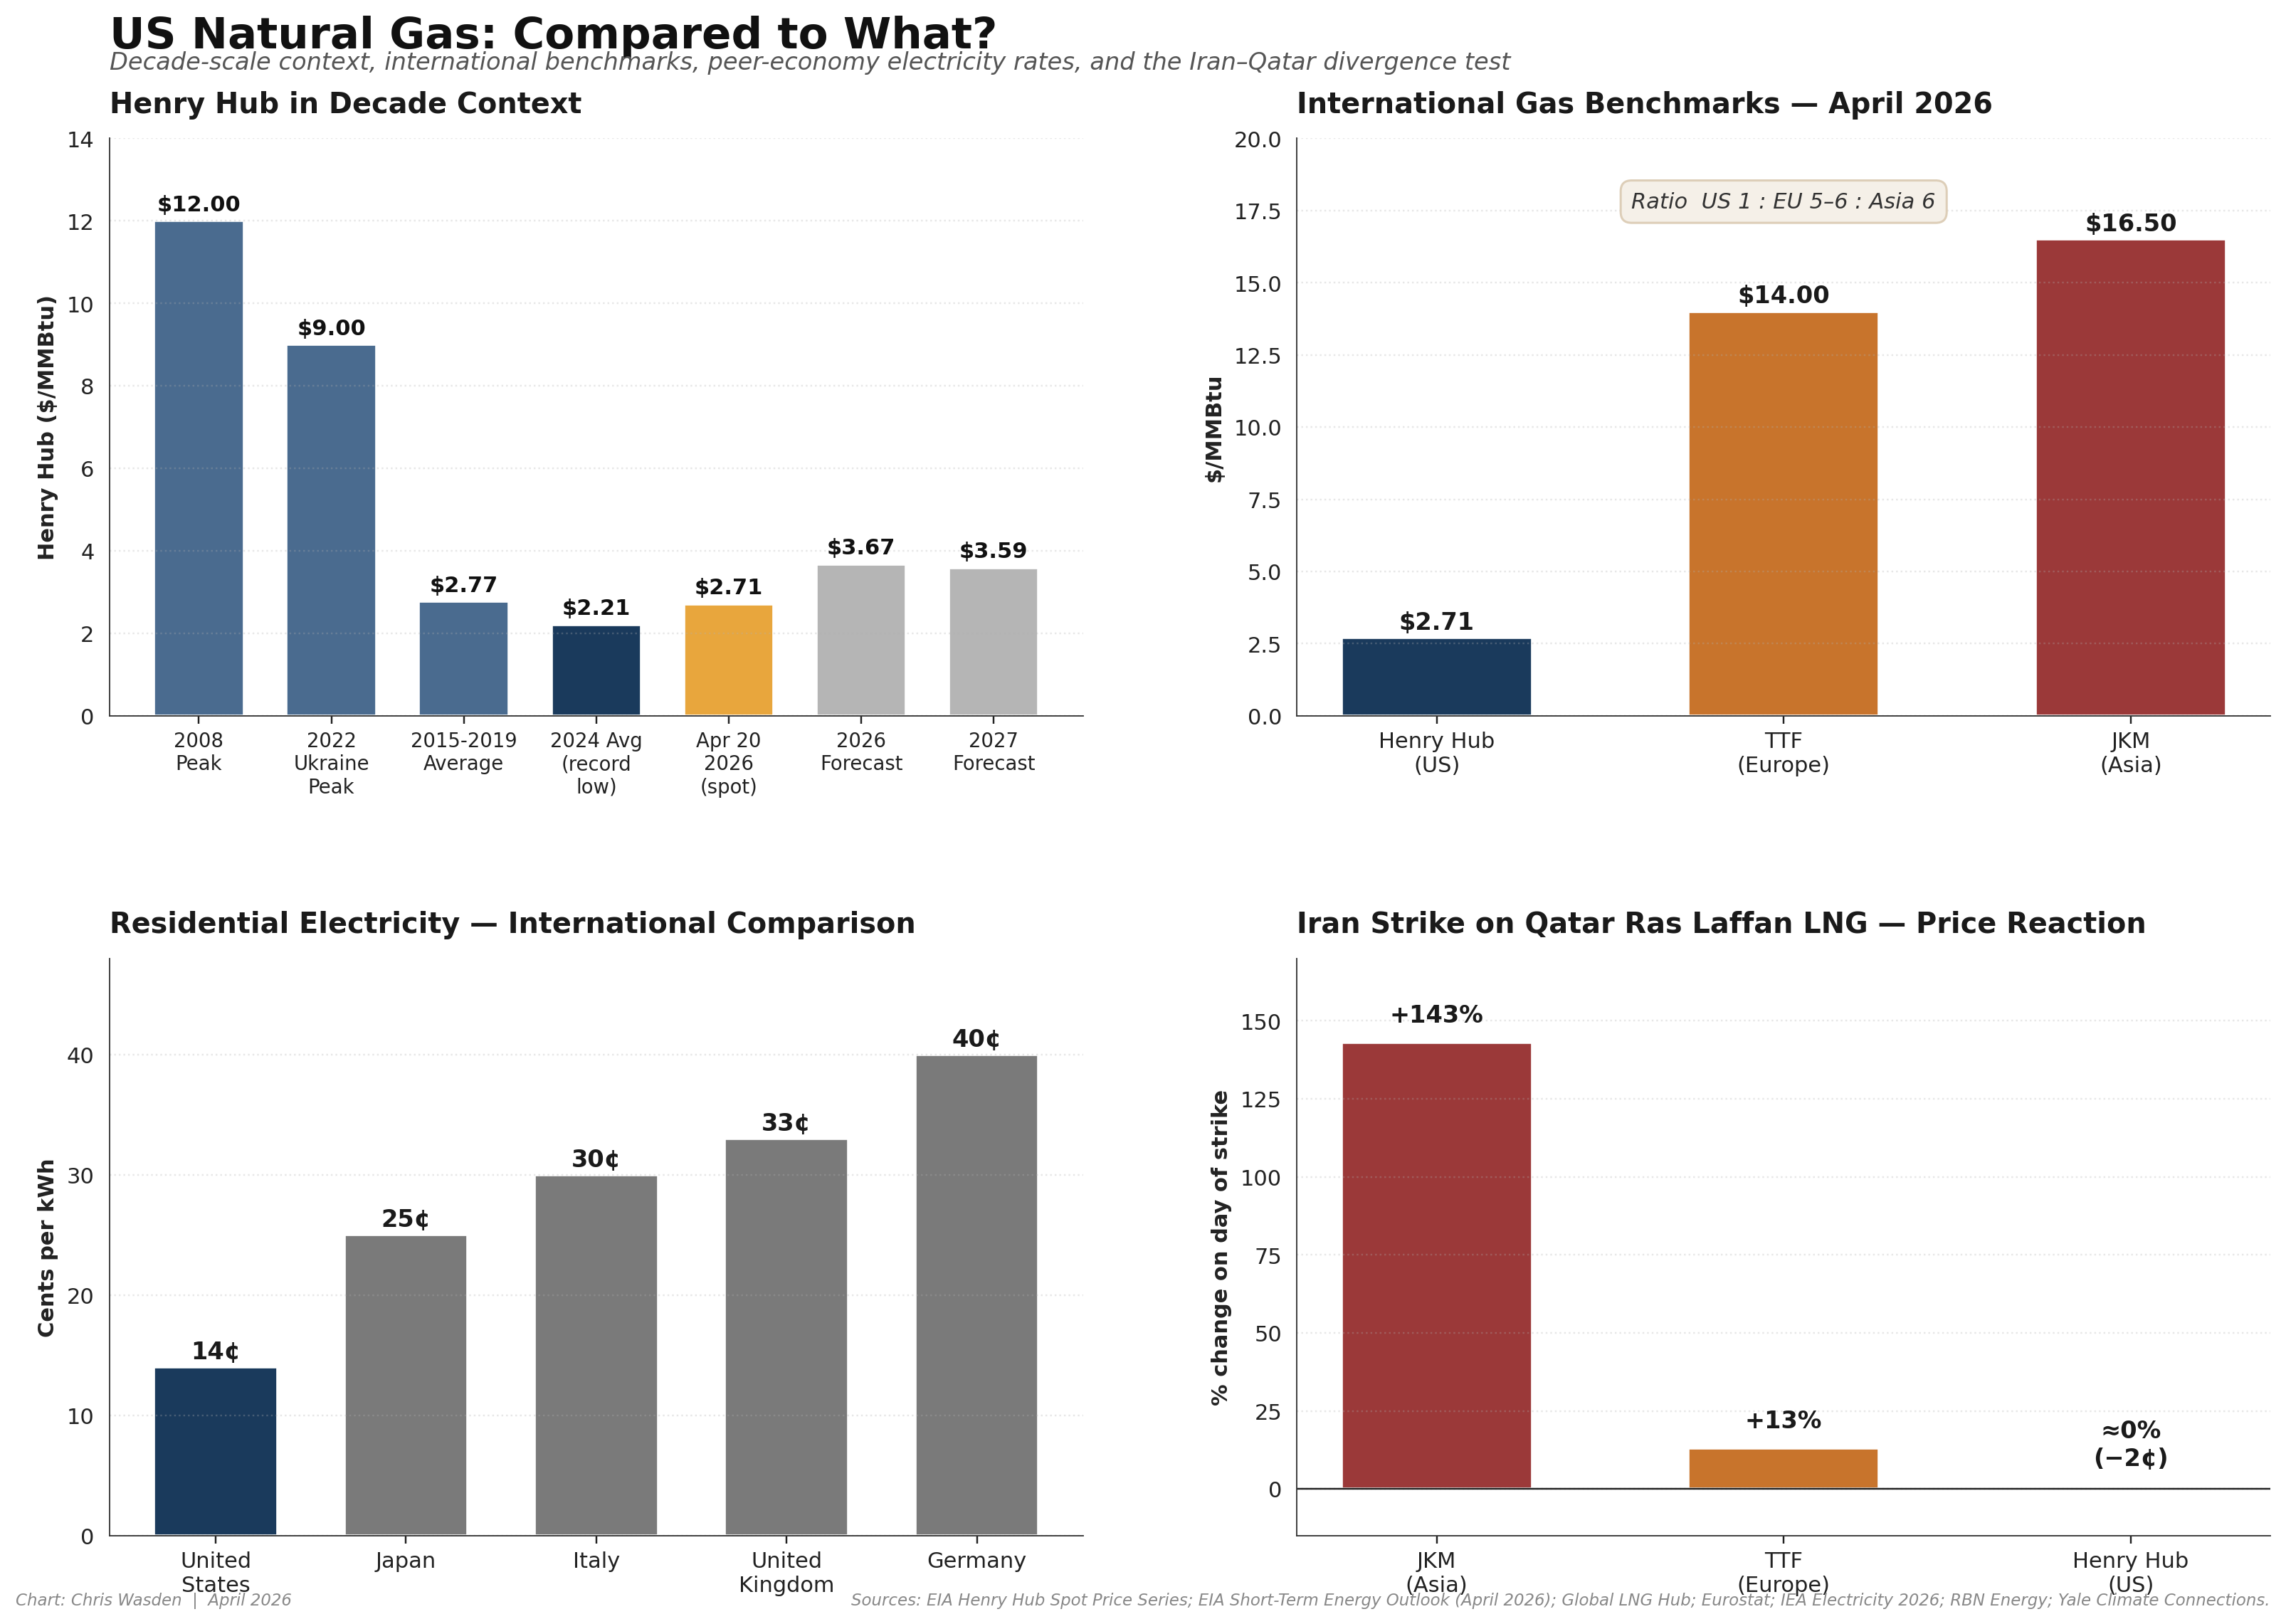
The claim that US gas prices have “doubled” does not survive a decade-scale chart. It doesn’t even survive a five-year chart.
Now look at the international comparison. The same week Henry Hub was at $2.71, the Dutch Title Transfer Facility — Europe’s benchmark — traded at $13–15. The Japan-Korea Marker, Asia’s benchmark, was in the high $16s. The ratio is US 1 : EU 5–6 : Asia 6. That cost advantage translates directly into electricity prices. US residential rates run at 10–18 cents per kilowatt-hour depending on the state. Germany’s run at 40. The United Kingdom’s at 33. Italy’s at 30. Japan’s at 25. American households pay roughly half to one-third what their peer-economy counterparts pay for the same service, and the structural reason is that we produce our own gas at Henry Hub prices rather than importing it at TTF or JKM prices.
The single cleanest demonstration of that structural advantage came during the current Iran conflict. When Iran struck Qatar’s Ras Laffan LNG complex — taking roughly 12.8 million tons per year of capacity offline — the Japan-Korea Marker surged as much as 143% on the day. The Dutch Title Transfer Facility jumped 13%. And Henry Hub fell two cents. Cumulatively, since the Iran conflict began, Henry Hub is up approximately 8%. Yale Climate Connections described the US benchmark as “holding steady around $3 per million British thermal units because of the country’s vast supply.”
That single set of numbers is worth more than any policy argument. It demonstrates empirically that the American domestic energy system is structurally decoupled from Middle Eastern supply shocks in a way that no other major economy’s is. The same event that raised Asian industrial gas costs by 143% moved the American benchmark by two cents.
The United States is the world’s largest natural gas producer — about 24% of global production, with 2025 marketed output setting a record at 118.5 billion cubic feet per day. It is the world’s largest LNG exporter — 111 million tons in 2025, the first country in history to cross 100 Mt in a single year. Russia, the number-two producer, outputs roughly 60% of US volumes. The video’s implication that gas prices are spiking because of AI demand or geopolitical shocks does not survive any of these comparisons.
Question Three: Compared to What? (Profitability)
The video’s most common refrain — that no AI company except Nvidia has turned a profit in the four years since ChatGPT launched — is structurally the same critique that would have disqualified every general-purpose technology in economic history.
In 1987, Robert Solow wrote in the New York Times Book Review that “you can see the computer age everywhere but in the productivity statistics.” He won the Nobel Prize in Economics the same year. His observation captured a real puzzle: the 1980s investment boom in computers was not showing up in measured productivity. Paul David’s 1990 paper “The Dynamo and the Computer” answered why. Electricity was commercially introduced in 1882 with Edison’s Pearl Street station, but measurable productivity gains did not arrive until the 1920s — a forty-year lag — because factories had to be physically rebuilt around individual unit drives rather than retaining line-shaft architecture around a central steam engine. Until the redesign, electricity captured almost none of its productive potential.
The computer productivity resurgence arrived a decade-plus after the 1980s investment boom. US nonfarm business labor productivity averaged 1.5% annually from 1974 to 1995, then accelerated to 2.5% from 1995 to 2001 and 3.7% from 2001 to 2004. Jorgenson, Ho, and Stiroh attributed roughly half of that acceleration to IT capital deepening and IT-producing-sector total factor productivity. Ben Bernanke’s 2006 Federal Reserve speech on productivity declared the Solow paradox resolved.
The dot-com telecom bubble produced the sharpest version of the pattern. Between 1996 and 2001, telecom companies invested more than $500 billion in fiber, switches, and wireless networks. By 2005, approximately 85% of that fiber was still dark. Bandwidth prices had collapsed 90%. The companies that built the fiber went bankrupt in waves. And yet YouTube, founded in 2005, and Amazon Web Services, founded in 2006, were built on exactly that dark fiber — as was the entire broadband economy that has dominated the two decades since. The bubble destroyed equity value and created durable public infrastructure. The failure was not that the technology was wrong. The failure was the timeline.
Brynjolfsson, Rock, and Syverson formalized this pattern in their 2021 paper “The Productivity J-Curve.” General-purpose technologies require massive intangible complements — process redesign, retraining, organizational adaptation — that are expensed as current cost rather than capitalized as investment. Measured total factor productivity therefore falls during the investment phase before rising as the complements mature. The authors document a 15.9% understatement of TFP by end-2017 when intangibles are accounted for properly. The late-1990s productivity boom was larger and started earlier than the official statistics showed, and a comparable understatement is plausibly occurring right now.
The adoption-to-productivity lag has also been compressing with each successive general-purpose technology. Electricity took forty years. PCs took fifteen to twenty. The commercial internet took ten to fifteen. Smartphones took five to ten. Generative AI reached 100 million users in two months, and by mid-2024, 26.4% of US workers were using it at work. McKinsey moved its midpoint for automation of half of current work activities a full decade earlier than its 2017 forecast. Goldman Sachs Research projects AI could lift US annual labor productivity growth by about 1.5 percentage points over a decade, with measurable GDP impact beginning in 2027. Even Daron Acemoglu’s skeptical floor — under 0.7% cumulative total factor productivity gain over ten years — would still represent the largest single contribution of any single technology in that window.
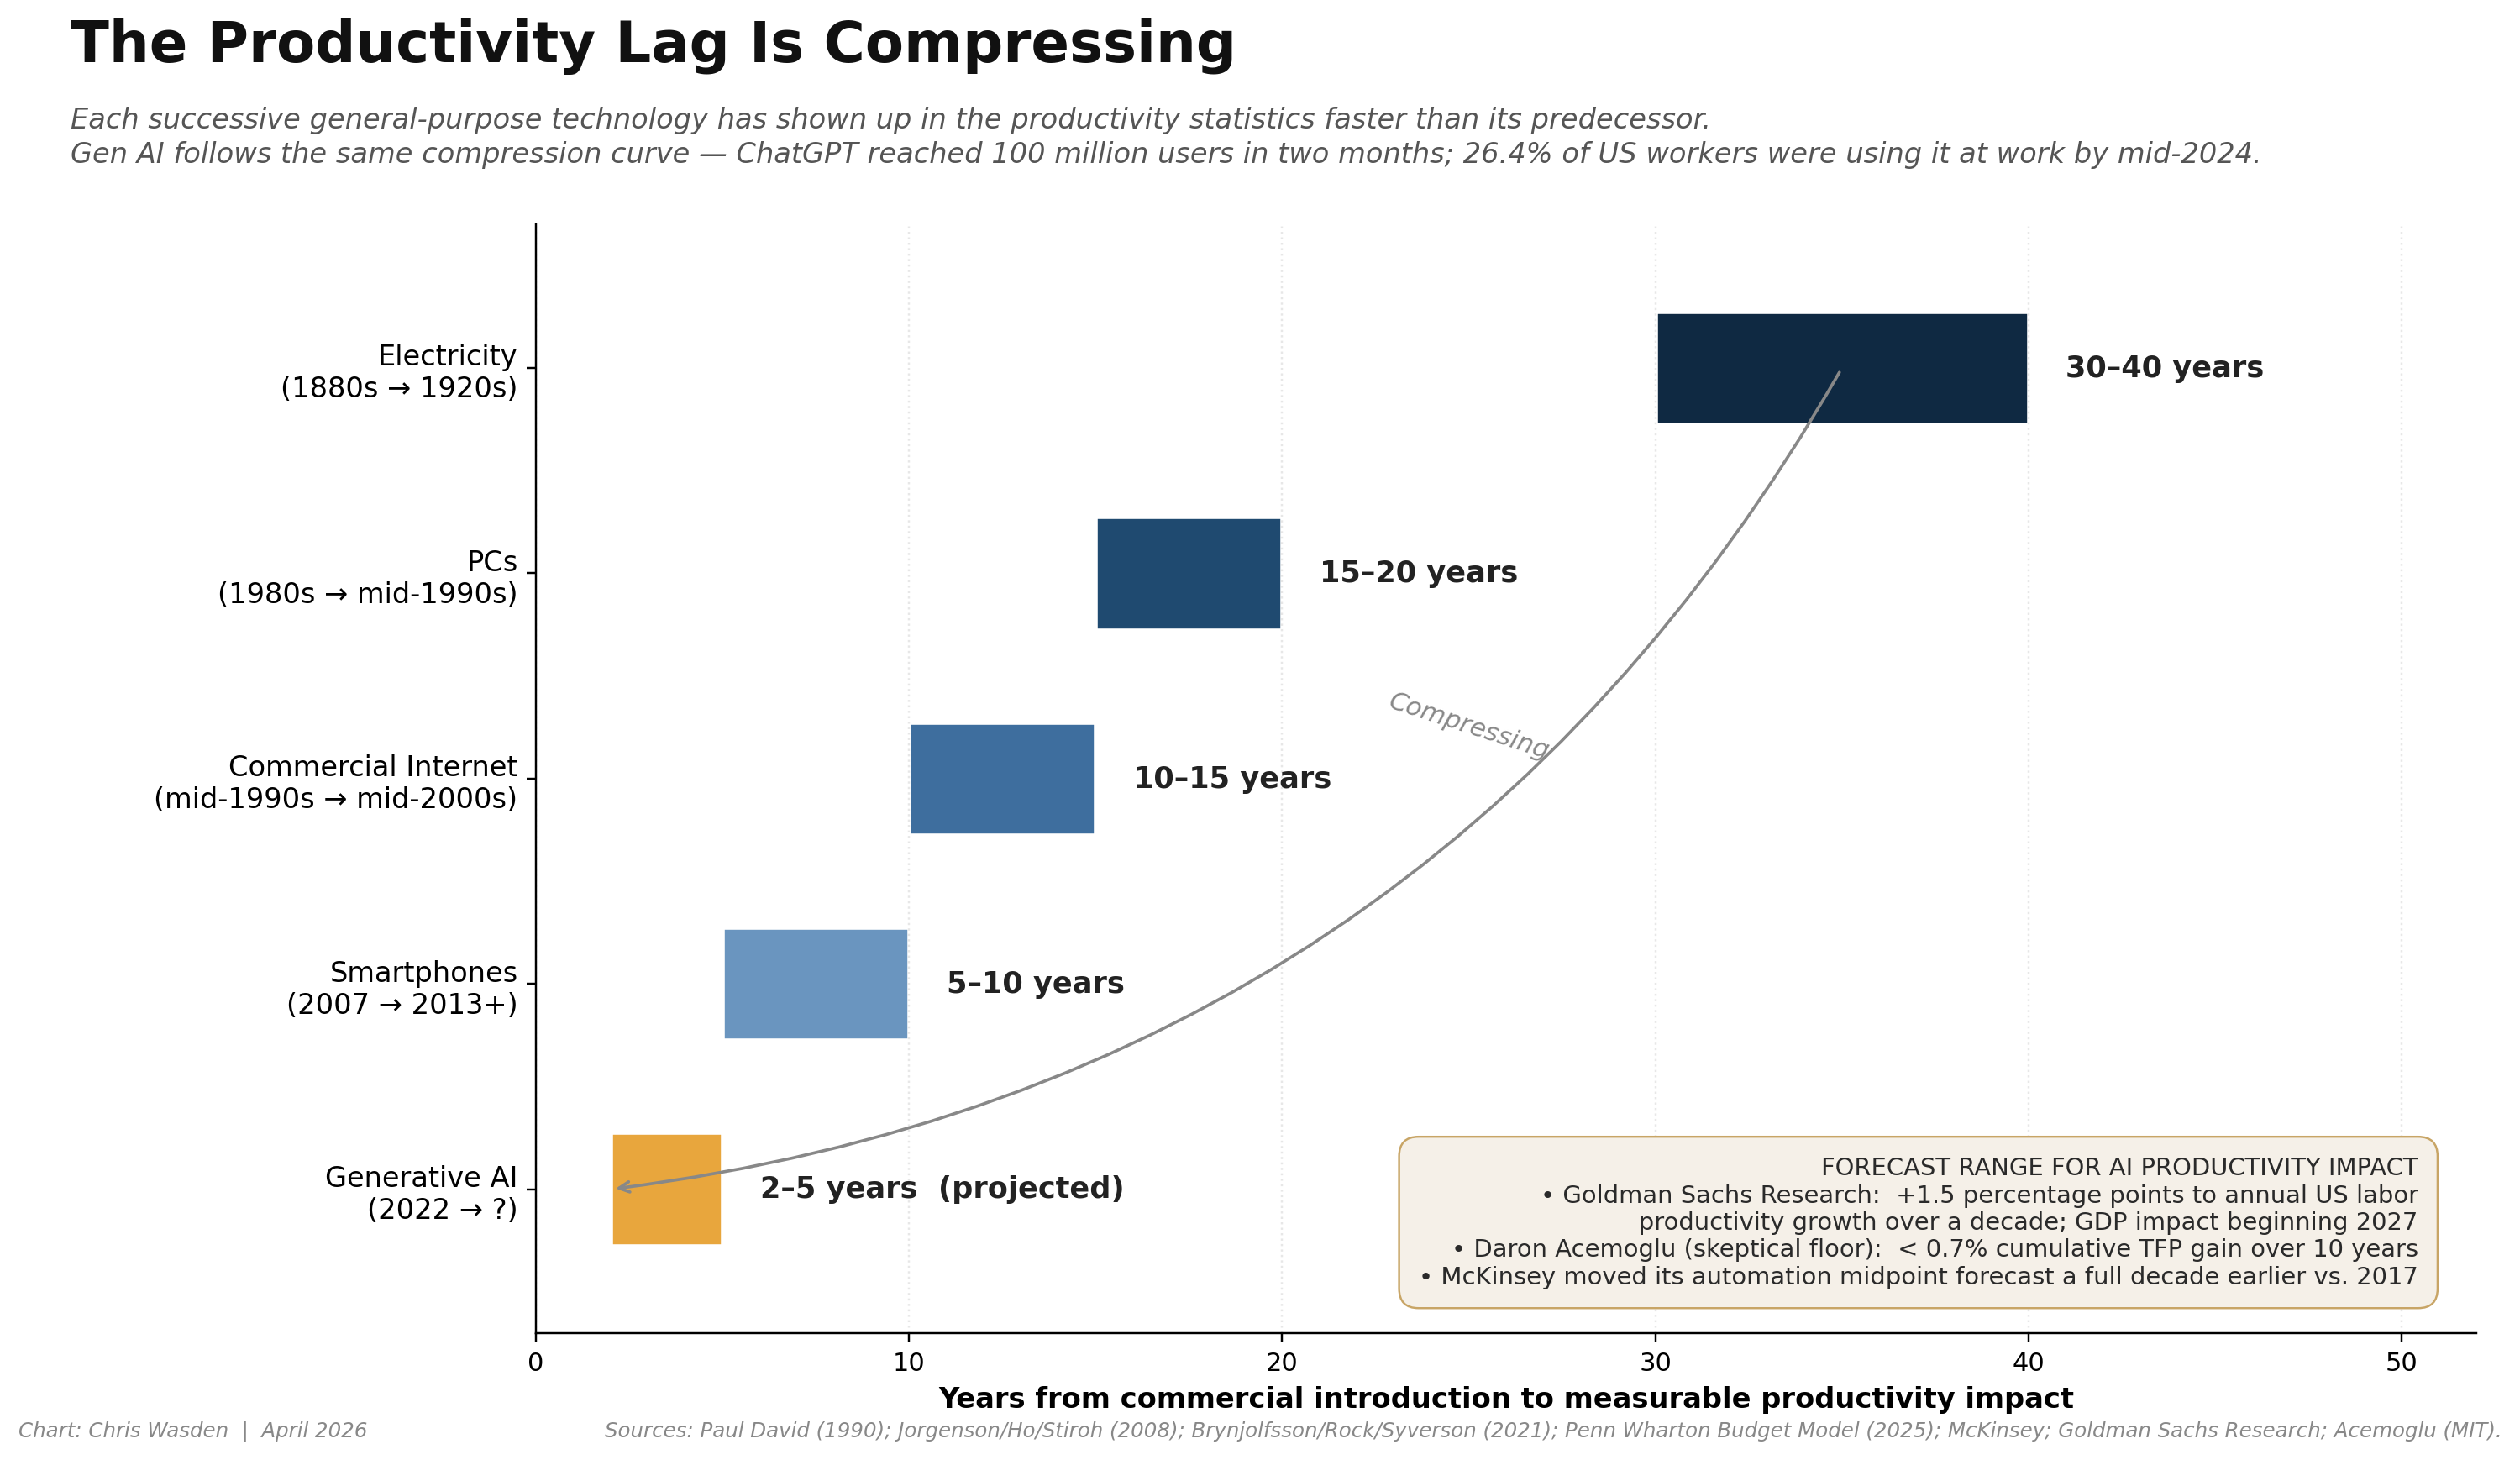
Asking whether OpenAI is profitable in 2026 is asking Amazon the same question in 1999. In both cases the measured profit is downstream of a capex cycle whose output is measured in decades, and the shape of the return is a J-Curve, not a straight line. Demanding instant profitability is a category error against the historical baseline.
What This Actually Is
Once all three “compared to what?” tests are applied, the underlying pattern becomes visible. The AI capex cycle is running into the same physical bottleneck every previous infrastructure build-out ran into: the interconnection, transformer, and substation layer of the electricity grid. The bottleneck is real. It is severe. It is worsening. And it is the consequence of two decades of under-investment in delivery infrastructure, not of AI demand.
The signature of this kind of bottleneck in capex data is the bullwhip effect. When the critical input has a multi-year queue, every buyer who wants capacity in 2028 has to order in 2025 regardless of whether the site is ready. Inventory grows ahead of sited deployment. Two buildings sit offline in Santa Clara because the utility can’t connect them. Stargate Abilene gets shelved because the transformer order slipped. Nvidia’s inventory doubles because TSMC, Wolfspeed, and every upstream supplier is also ordering against three-to-four-year lead times. None of that is a bubble. All of it is the predictable signature of an exponential demand curve meeting a linear supply chain.
The Creative response is already underway. Microsoft restarted Three Mile Island’s Unit 1 reactor through a twenty-year power purchase agreement with Constellation. Google committed to a fleet of small modular reactors built by Kairos Power. Amazon invested $500 million in X-energy. Meta signed for 2,176 megawatts across Ohio nuclear plants. These are not virtue plays. They are the data-center operators solving for the delivery bottleneck by securing baseload power directly.
On the grid hardware itself, Andrew Baglino left Tesla after nearly two decades running powertrains, batteries, and charging infrastructure, and founded Heron Power to apply silicon-carbide semiconductors to the grid layer. SiC is an American technology — developed at North Carolina State University, commercialized by Cree (now Wolfspeed) in Durham. It enables solid-state transformers that consolidate voltage conversion, fault isolation, power-factor correction, and frequency regulation into a single programmable package, modular, bidirectional, and updateable by firmware. Grid-enhancing technologies — advanced power-flow controllers, dynamic line ratings, topology optimization — can add 20% to 40% of capacity to existing transmission lines without new construction. Global grid capital expenditure hit $470 billion in 2025, up 16% year-over-year, with the United States alone accounting for $115 billion. The market is pricing in exactly the delivery-layer story the skeptic narrative is missing.
The TTF Frame
Under the Tension Transformation Framework, the How Money Works video operates in Skeptic or Reformer identity. It looks at strained infrastructure and predicts correction. That is a legitimate posture, and the data it surfaces are legitimate data. What distinguishes the Architect identity is what the diagnostician does next. Charif Souki saw the shale revolution and converted an import terminal to an export terminal against every expert’s advice — which is why, when Qatar’s LNG complex went offline, Henry Hub fell two cents. George Mitchell cracked shale when the majors had given up. Fervo Energy applied oilfield drilling to geothermal. Baglino left Tesla to apply power electronics to the grid. Each of them saw the same constraint the skeptics saw and built around it rather than predicting collapse.
The tension is not AI ambition versus economic reality. The tension is exponential generation abundance versus linear delivery infrastructure. Three response patterns are available. The Maladaptive response is the moratorium wave now in ten states — Louisiana, Michigan, New York, Ohio, Virginia, Maine, and others — attempting to block data centers from the communities where they would generate the capital for grid upgrades those same communities need. The Adaptive response is the wait-for-reimbursement posture: build around the constraint, lobby for capacity-market reform, hope the transformer supply chain recovers on its own. The Creative response is what is actually being built: the AWS Model, where data centers fund household energy upgrades that free up grid capacity for industrial load. The Mississippi pattern, where Entergy absorbed $1 billion in grid modernization at zero residential cost. The Utah sandbox for AI governance. The SiC-based solid-state transformer rollout. Nuclear power purchase agreements providing baseload. State-level experimentation generating the learning that centralized planning cannot match.
America’s three structural superpowers — Federalism, Mobility, Free Speech — are doing the work they were designed to do. Fifty states are running parallel experiments in how to absorb data-center load. Developers are moving projects toward the states that solve it first. Independent researchers at SemiAnalysis, Lawrence Berkeley National Laboratory, Brynjolfsson’s Stanford Digital Economy Lab, and Heron Power are publicly correcting the misdiagnosis that politicians and media have been running on. The system is working. What is required is not moratoriums. What is required is to keep building the delivery layer, keep running the state laboratories, and keep trusting the exponential curves that have resolved every prior iteration of this debate.
The Three Questions, Together
Three “compared to what?” tests. Three missing counterfactuals. One common failure.
Rhode Island’s bills are rising faster than Texas’s because New England has old transformers and no pipeline access, not because of AI. The states with the most data centers are paying less than the national average. PG&E projects data centers could reduce California bills. The “AI is raising your bill” narrative fails the state-level test.
Henry Hub is $2.71 in a world where Asian gas trades at $16 and European gas at $13 — a decade below the 2008 peak and below the 2024 inflation-adjusted all-time low. When Iran struck Qatar, Asian prices surged 143% and Henry Hub fell two cents. The “gas prices have doubled” narrative fails the decade-scale and international tests.
Every general-purpose technology in economic history has produced a measured productivity dip during its intangible-capex phase, followed by acceleration — electricity’s forty-year lag, the computer’s fifteen, the internet’s ten, the smartphone’s five, compounding faster each time. The dot-com overbuild produced the fiber that carries YouTube, AWS, and modern broadband. The “AI isn’t profitable yet” critique fails the historical test.
The people predicting a bubble are asking the same question 1999 skeptics asked about Amazon and 1987 skeptics asked about computers. They were wrong in each case. The discipline that makes this analysis different is not optimism. It is the “compared to what?” test applied at every turn. Apply it once and the state-level data dissolves the electricity story. Apply it twice and the international data dissolves the gas story. Apply it three times and the J-Curve dissolves the profitability story.
The real AI bubble is the one we would create by demanding profitability now. Pull capital out of the delivery-layer build-out because OpenAI doesn’t yet clear GAAP, and you hand the next decade of AI to the three or four companies whose balance sheets can absorb the J-Curve alone. That is the outcome the skeptic narrative claims to fear. It is also the outcome the skeptic narrative would guarantee. The delivery layer is the story. And the question is not whether this infrastructure will be absorbed. The question is which states, which companies, and which communities figure out how to absorb it first.
Chris Wasden, EdD, is a healthcare strategist, author, educator, and creator of the Tension Transformation Framework. This analysis draws on research assembled in April 2026 in response to the “How Money Works” YouTube video “50% Of AI Data Centers Have Quietly Been Cancelled Or ‘Delayed’” and the broader AI-capex skeptic narrative circulating in business media.
Selected sources: Institute for Energy Research state-level residential rate analysis (2025); SemiAnalysis “Are AI Datacenters Increasing Electric Bills for American Households?”; Lawrence Berkeley National Laboratory 2024 US Data Center Energy Usage Report; Reason, “The Data Center Price Myth” (December 2025); EIA Henry Hub Spot Price Series and Short-Term Energy Outlook (April 2026); Yale Climate Connections on Iran conflict gas-price divergence; Paul A. David, “The Dynamo and the Computer” (AER 1990); Jorgenson, Ho, and Stiroh, “A Retrospective Look at the U.S. Productivity Growth Resurgence” (JEP 2008); Brynjolfsson, Rock, and Syverson, “The Productivity J-Curve” (AEJ: Macro 2021); Andrew Baglino, “America’s Energy Problem Isn’t Supply. It’s Delivery” (a16z, April 2026). Full 95-citation source bibliography available in the companion research addendum.